

4149results found for 'Analysis'
Price
News
- [SMM Coal and Coke Shipping] China's coal port arrivals last week were 8.46 million mt, up 2% WoW and down 3% YoY.
Port departures: According to SMM tracking, global coal port departures last week were 27.77 million mt, down 5% WoW and down 7% YoY, with cumulative port departures in 2026 at 1.1514 billion mt. Port arrivals: According to SMM tracking, China's coal port arrivals last week were 8.46 million mt, up 2% WoW and down 3% YoY, with cumulative port arrivals in 2026 at 302.2 million mt. 1 . For data involved in the report, please log in to the SMM database ( https://data-pro.smm.cn/) to view 2 . For details on SMM steel shipping data, steel industry information, analysis reports, databases, and more, please contact the SMM Steel Division Hou Lei 021-51595960
Oct 18, 2026 17:59 (GMT+8) - [SMM Analysis] Overseas Primary Aluminum Market Remains Weak; Offer Prices Under Pressure Across Major Markets
The overseas primary aluminum market continued its weak tone this week. Soft demand remained the core issue across all major markets, with offer prices generally under pressure in Japan, South Korea, Thailand, the United States and China. Market activity was muted, buyers and sellers remained locked in a standoff, and the market lacked clear directional guidance overall. Japan: MJP negotiations continue; market sentiment stays subdued The Japanese market remained quiet this week, with the focus still on the progress of Q4 MJP negotiations. Some sellers are still negotiating premium levels with buyers, but the two sides diverge significantly on price expectations and talks are progressing slowly. As a result, the MJP market stays depressed, with limited spot transactions heard. Most participants are adopting a wait-and-see stance until quarterly pricing is settled before acting. The standoff between the two sides has left the market without transactional momentum. Vietnam: Demand exists but participation is insufficient; prices hover at low levels Although some demand was present in the Vietnamese market this week, market activity remained limited. Notably, only a few sellers participated in quoting during buyer inquiries, indicating clearly insufficient market participation. Buyers and sellers struggled to connect effectively, and transactions were scarce. With limited support from the demand side and weak willingness among sellers to quote, local prices stayed at relatively low levels. Combined with waning trader enthusiasm and slower terminal procurement, the premium level in the Vietnamese market is unlikely to gain effective support in the near term and is expected to remain at the low end. United States: Market weak and stagnant; trading volume limited The US market performed weakly this week, appearing largely stagnant with limited trading volume. Although some high-priced cargo occasionally traded, volumes were small and insufficient to effectively lift the overall market. The demand side offered no bright spots, with downstream purchasing driven mainly by essential needs and a strong wait-and-see sentiment prevailing. Both buyers and sellers are awaiting clearer signals. Prices are expected to fluctuate within a narrow range in the near term, lacking a trend-driven move. South Korea: Market relatively chaotic; offer prices continue to decline The South Korean market remained relatively chaotic this week, with offer prices extending their downward trend. The supply structure is complex, with quotes for aluminum ingots from different sources varying notably and quoted ranges widely dispersed. Buyers are pressing hard for lower prices, while a significant gap remains between sellers' willingness to sell and buyers' acceptance levels, slowing the pace of transactions. With no marked improvement on the demand side, the market lacks supportive factors, and the price center is expected to keep shifting lower. Going forward, attention should be paid to the digestion of low-priced cargo and changes in buyer acceptance. Thailand: Rebound lacks momentum; offers return to a downward track The Thai market saw a modest rebound last week, but it did not last. Offer prices began drifting lower again from the start of this week. The earlier rebound was more of a short-term sentiment repair, lacking sustained demand support. As the market reverted to fundamentals, sellers loosened their quotes again to facilitate shipments amid missing orders and cautious downstream purchasing, dragging the overall price center lower. In the near term, the weak pattern in the Thai market is unlikely to change, and prices may still have room to fall further. China: Weak demand; both USD and RMB prices cut The Chinese market also came under pressure this week, with both USD and RMB prices declining. The core reason remains overly weak demand — the market lacks effective buyers, inquiries are scarce, and volumes are difficult to scale up. Sellers' selling pressure continues to accumulate, forcing repeated price concessions. In the near term, unless demand shows visible improvement, the Yangshan premium is expected to remain weak.
Oct 16, 2026 18:28 (GMT+8) - Ex-China aluminum market remains weak, spot offers in major markets fall under pressure [SMM Analysis]
This week, the overseas aluminum market overall remained in the doldrums. Weak demand continued to be the core issue across major markets, with offer prices in Japan, South Korea, Thailand, the US, and China generally under pressure. Trading activity was sluggish, and the tug-of-war between sellers and buyers persisted, with the market lacking clear directional guidance overall. Japan: MJP negotiations continue, market sentiment remains subdued The Japanese market remained relatively quiet this week, with focus still on the progress of Q4 MJP negotiations. Some sellers are still negotiating premiums with buyers, but the two sides have significant differences in price expectations, and negotiations are progressing slowly. As a result, the MJP market remains subdued, with limited spot market transactions reported. Most participants are adopting a wait-and-see approach, waiting for quarterly pricing to be finalized before taking action. The stalemate between the two sides has left the market lacking trading momentum. Vietnam: Demand exists but participation is insufficient, prices linger at low levels Although there was some demand in the Vietnamese market this week, market activity remained limited. Notably, only some sellers participated in quoting during buyer inquiries, and market participation was clearly insufficient. Buyers and sellers struggled to connect effectively, resulting in very few transactions. With limited demand-side support and weak willingness among sellers to quote, local prices remained at relatively low levels. Coupled with waning trader participation and a slowdown in end-user procurement pace, premium levels in the Vietnamese market are unlikely to find effective support in the short term and are expected to remain at low levels. US: Market sluggish and stagnant, trading volume limited The US market showed sluggish performance this week, remaining largely stagnant with limited trading volume. Although some high-priced cargoes were occasionally traded, the transaction volumes were relatively small and insufficient to provide meaningful momentum to the overall market. The demand side lacked highlights, with downstream procurement mainly driven by immediate needs and strong wait-and-see sentiment prevailing in the market. Both buyers and sellers are waiting for clearer signals, and prices are expected to move sideways in the short term without a clear trend. South Korea: Market relatively chaotic, offer prices continue to decline The South Korean market remained relatively chaotic this week, with offer prices continuing to trend downward. The supply structure was complex, with notable differences in quotes for aluminum ingots from different sources and a widely dispersed quotation range. Buyers showed a strong tendency to push for lower prices, while there was a significant gap between sellers' willingness to sell and buyers' acceptance levels, slowing transaction progress. With no clear improvement on the demand side, the market lacks positive support, and the price center is expected to continue shifting downward. Attention should be paid to the absorption of low-priced cargoes and changes in buyer acceptance levels. Thailand: Insufficient rebound momentum, offers back on downward trajectory The Thai market saw a slight rebound last week, but it was short-lived. From the beginning of this week, offer prices have been falling continuously again. The earlier rebound was more a reflection of short-term sentiment repair, lacking sustained demand support. As the market returned to fundamentals, with orders absent and downstream purchasing cautious, sellers loosened their quotes again to facilitate shipments, and the overall price center moved lower once more. In the short term, the weak pattern in the Thai market is unlikely to change, and prices may still have downside. China: Weak demand, both USD and RMB prices lowered The Chinese market was also under pressure this week, with both USD and RMB prices showing a downward trend. The core reason remains that current demand is too weak, the market lacks effective buyers, inquiries are scarce, and transactions are hard to scale up. Suppliers' shipment pressure continued to accumulate, and quotes had to be repeatedly lowered. In the short term, if there is no clear improvement on the demand side, the Yangshan premium is expected to remain in the doldrums. [Data source statement: Except for public information, all other data are processed by SMM based on public information, market communication, and SMM's internal database models, and are for reference only and do not constitute decision-making advice.] Data source: SMM
Oct 16, 2026 18:24 (GMT+8) - China Proposes Tighter Solar Technology Export Controls: What Next for the Ex-China Region? [SMM Analysis]
On 16 October, China's Ministry of Commerce (MOFCOM) and Ministry of Science and Technology announced proposed revisions to the Catalogue of Technologies Prohibited and Restricted from Export, alongside temporary pre-export registration requirements for the technologies concerned. The solar sector accounts for 12 technologies covering polysilicon, wafer and cell manufacturing. Certain key and core equipment incorporating these technologies also falls within the scope.
Oct 16, 2026 18:21 (GMT+8) - [SMM Analysis] Weak Demand and Rising Substitution Advantage Push High-Grade NPI Price Center Downward
[SMM Analysis: Weak Demand and Rising Substitution Advantage Drag Down High-Grade NPI Price Center] The average price of SMM 10-12% high-grade NPI fell 7.9 yuan/nickel unit WoW to 1,029.4 yuan/nickel unit (ex-factory, tax included). The average price of the Indonesian NPI FOB index fell 0.7 $/nickel unit WoW to 133.2 $/nickel unit. This week, the high-grade NPI market continued to drift lower, with the price center moving down steadily and bearish sentiment intensifying.
Oct 16, 2026 18:08 (GMT+8) - [SMM Analysis] Insufficient Momentum for Change, Grain-Oriented Silicon Steel Prices May Remain in the Doldrums in October
September Price Review : Source: SMM In September, mainstream grades of grain-oriented silicon steel (GO silicon steel) showed a weak and stable trend, with fluctuations narrowing for grades such as B23R085, B23P090, and 30G120, and the price center holding steady. The core benchmark B23R085 saw its monthly average price move sideways, with ample supply in the market and no significant improvement in the loose supply-demand pattern, which continued to weigh on prices. Based on the price forecast curve, there was insufficient momentum for a short-term upward rebound. Overall, demand for GO silicon steel in September lacked a strong boost, as downstream transformer enterprises mostly made just-in-time procurement with cautious stockpiling sentiment, resulting in a moderate pace of market transactions, persistent wait-and-see sentiment, and a market characterized mainly by weak and stable consolidation. Fundamental Analysis: Source: SMM In September, China's GO silicon steel production schedule edged up MoM, with steel mills raising their production plans and overall scheduled production remaining in a high range. In terms of product mix, HIB high-permeability GO silicon steel maintained its dominant position in production, while CGO conventional GO silicon steel remained at low output, as steel mills continued to shift production resources toward high-value-added HIB grades. Overall, September production schedule increased slightly, capacity deployment for HIB grades remained stable, and supply of high-permeability products was ample. New orders in the transformer industry were insufficient, downstream stocking willingness was weak, and supply growth further amplified supply pressure. With no significant contraction on the supply side, the loose supply-demand pattern was difficult to improve, exerting sustained pressure on spot prices. In October, China's GO silicon steel production schedule pulled back slightly MoM, with steel mills moderately lowering production plans based on downstream order conditions. In terms of product mix, HIB high-permeability GO silicon steel continued to dominate output, while CGO conventional GO silicon steel output remained low, with no significant change in the production structure. Overall, in October steel mills proactively fine-tuned their production schedules, making modest production cuts to ease supply pressure, but the adjustment was limited and HIB spot inventory remained ample. Transformer enterprises saw weak order follow-through, with procurement mostly consisting of just-in-time restocking, and demand showed no notable improvement. The modest production cuts were insufficient to drive effective inventory destocking, the loose supply-demand pattern persisted, and spot market conditions lacked upward momentum. Source: Public data, SMM In August 2026, new installations across power supply sources in the power grid continued to show a divergent pattern, with wind power and solar power remaining the core sources of demand for GO silicon steel, together accounting for the majority of total GO silicon steel consumption in the grid sector. Thermal power ranked second, while hydropower and nuclear power remained at low shares. In August, new wind power installations pulled back, while new solar installations held steady, providing only basic demand support for transformers and GO silicon steel. Growth in new installations of hydropower, thermal power, and nuclear power was weak, offering limited boost to GO silicon steel. Overall, in August, demand for grain-oriented silicon steel from the power grid still relied on wind and solar power installations as the demand base, but new installations were generally weak. Transformer manufacturers saw insufficient follow-up in new orders, and downstream continued the pattern of purchasing small orders as needed, with weak willingness to stockpile proactively. Overall demand lacked a strong boost, making it difficult to drive grain-oriented silicon steel prices upward. October price outlook: Looking ahead to October 2026, in terms of supply, China's total grain-oriented silicon steel production is expected to decline slightly. Mainstream state-owned steel mills will maintain normal production on their lines, with operating rates basically unchanged. High-end grades will be released in an orderly manner, while ordinary grades will remain in ample supply. On the demand side, China's "15th Five-Year Plan" ultra-high voltage projects continue to advance. In October, State Grid and China Southern Power Grid will continue to fulfill earlier tender orders. Downstream will shift from proactive stockpiling to purchasing as needed, with rigid demand support still present, but new purchasing momentum will weaken. In addition, the EU's new provisional safeguard measures on Chinese grain-oriented silicon steel will cause export cargoes to continue flowing back into the domestic market, impacting the market. On the cost side, the October hot-rolled coil market lacks a trending one-sided driver and is overall expected to maintain a weak consolidating pattern. Subsequent focus will be on post-holiday steel mill production cut pace, post-holiday end-user transaction recovery, and the latest policy developments. In summary, SMM expects grain-oriented silicon steel prices in October 2026 to remain in a consolidating and stable range overall, with insufficient momentum for either rise or fall. Data source statement: (Except for public information, all other data in this report are derived from public information (including but not limited to industry news, seminars, exhibitions, corporate financial reports, broker reports, National Bureau of Statistics data, customs import and export data, and various data published by major associations and institutions), market communication, and SMM's internal database models. They are produced through comprehensive analysis and reasonable inference by the research team, and are for reference only and do not constitute decision-making advice. Shanghai Metals Market reserves the final right of interpretation of the terms of this statement and retains the right to adjust and modify the content of the statement based on actual circumstances.
Oct 16, 2026 17:30 (GMT+8)
Announcements
Effective 12 Oct 2026, SMM launches two daily price points for HRC SAE1006 3.0*1250*C, CFR Surabaya, Indonesia (SMM-GS-HR-034) & HRC SAE1006 3.0*1250*C Indonesian-Origin CFR Vietnam (SMM-GS-HR-035)
PriceSep 29, 2026 13:17 (GMT+8)SMM to launch 10 Tokyo Steel Japan domestic rebar and HRC price points in JPY and USD on September 23, 2026, to improve access to pricing information.
PriceSep 18, 2026 17:27 (GMT+8)SMM will launch a weekly spot price for Japanese-origin A-grade copper cathodes delivered CIF Nhava Sheva, quoted in USD/tonne and updated every Wednesday at 12:00 PM IST from September 23, 2026.
PriceSep 16, 2026 14:37 (GMT+8)
Events
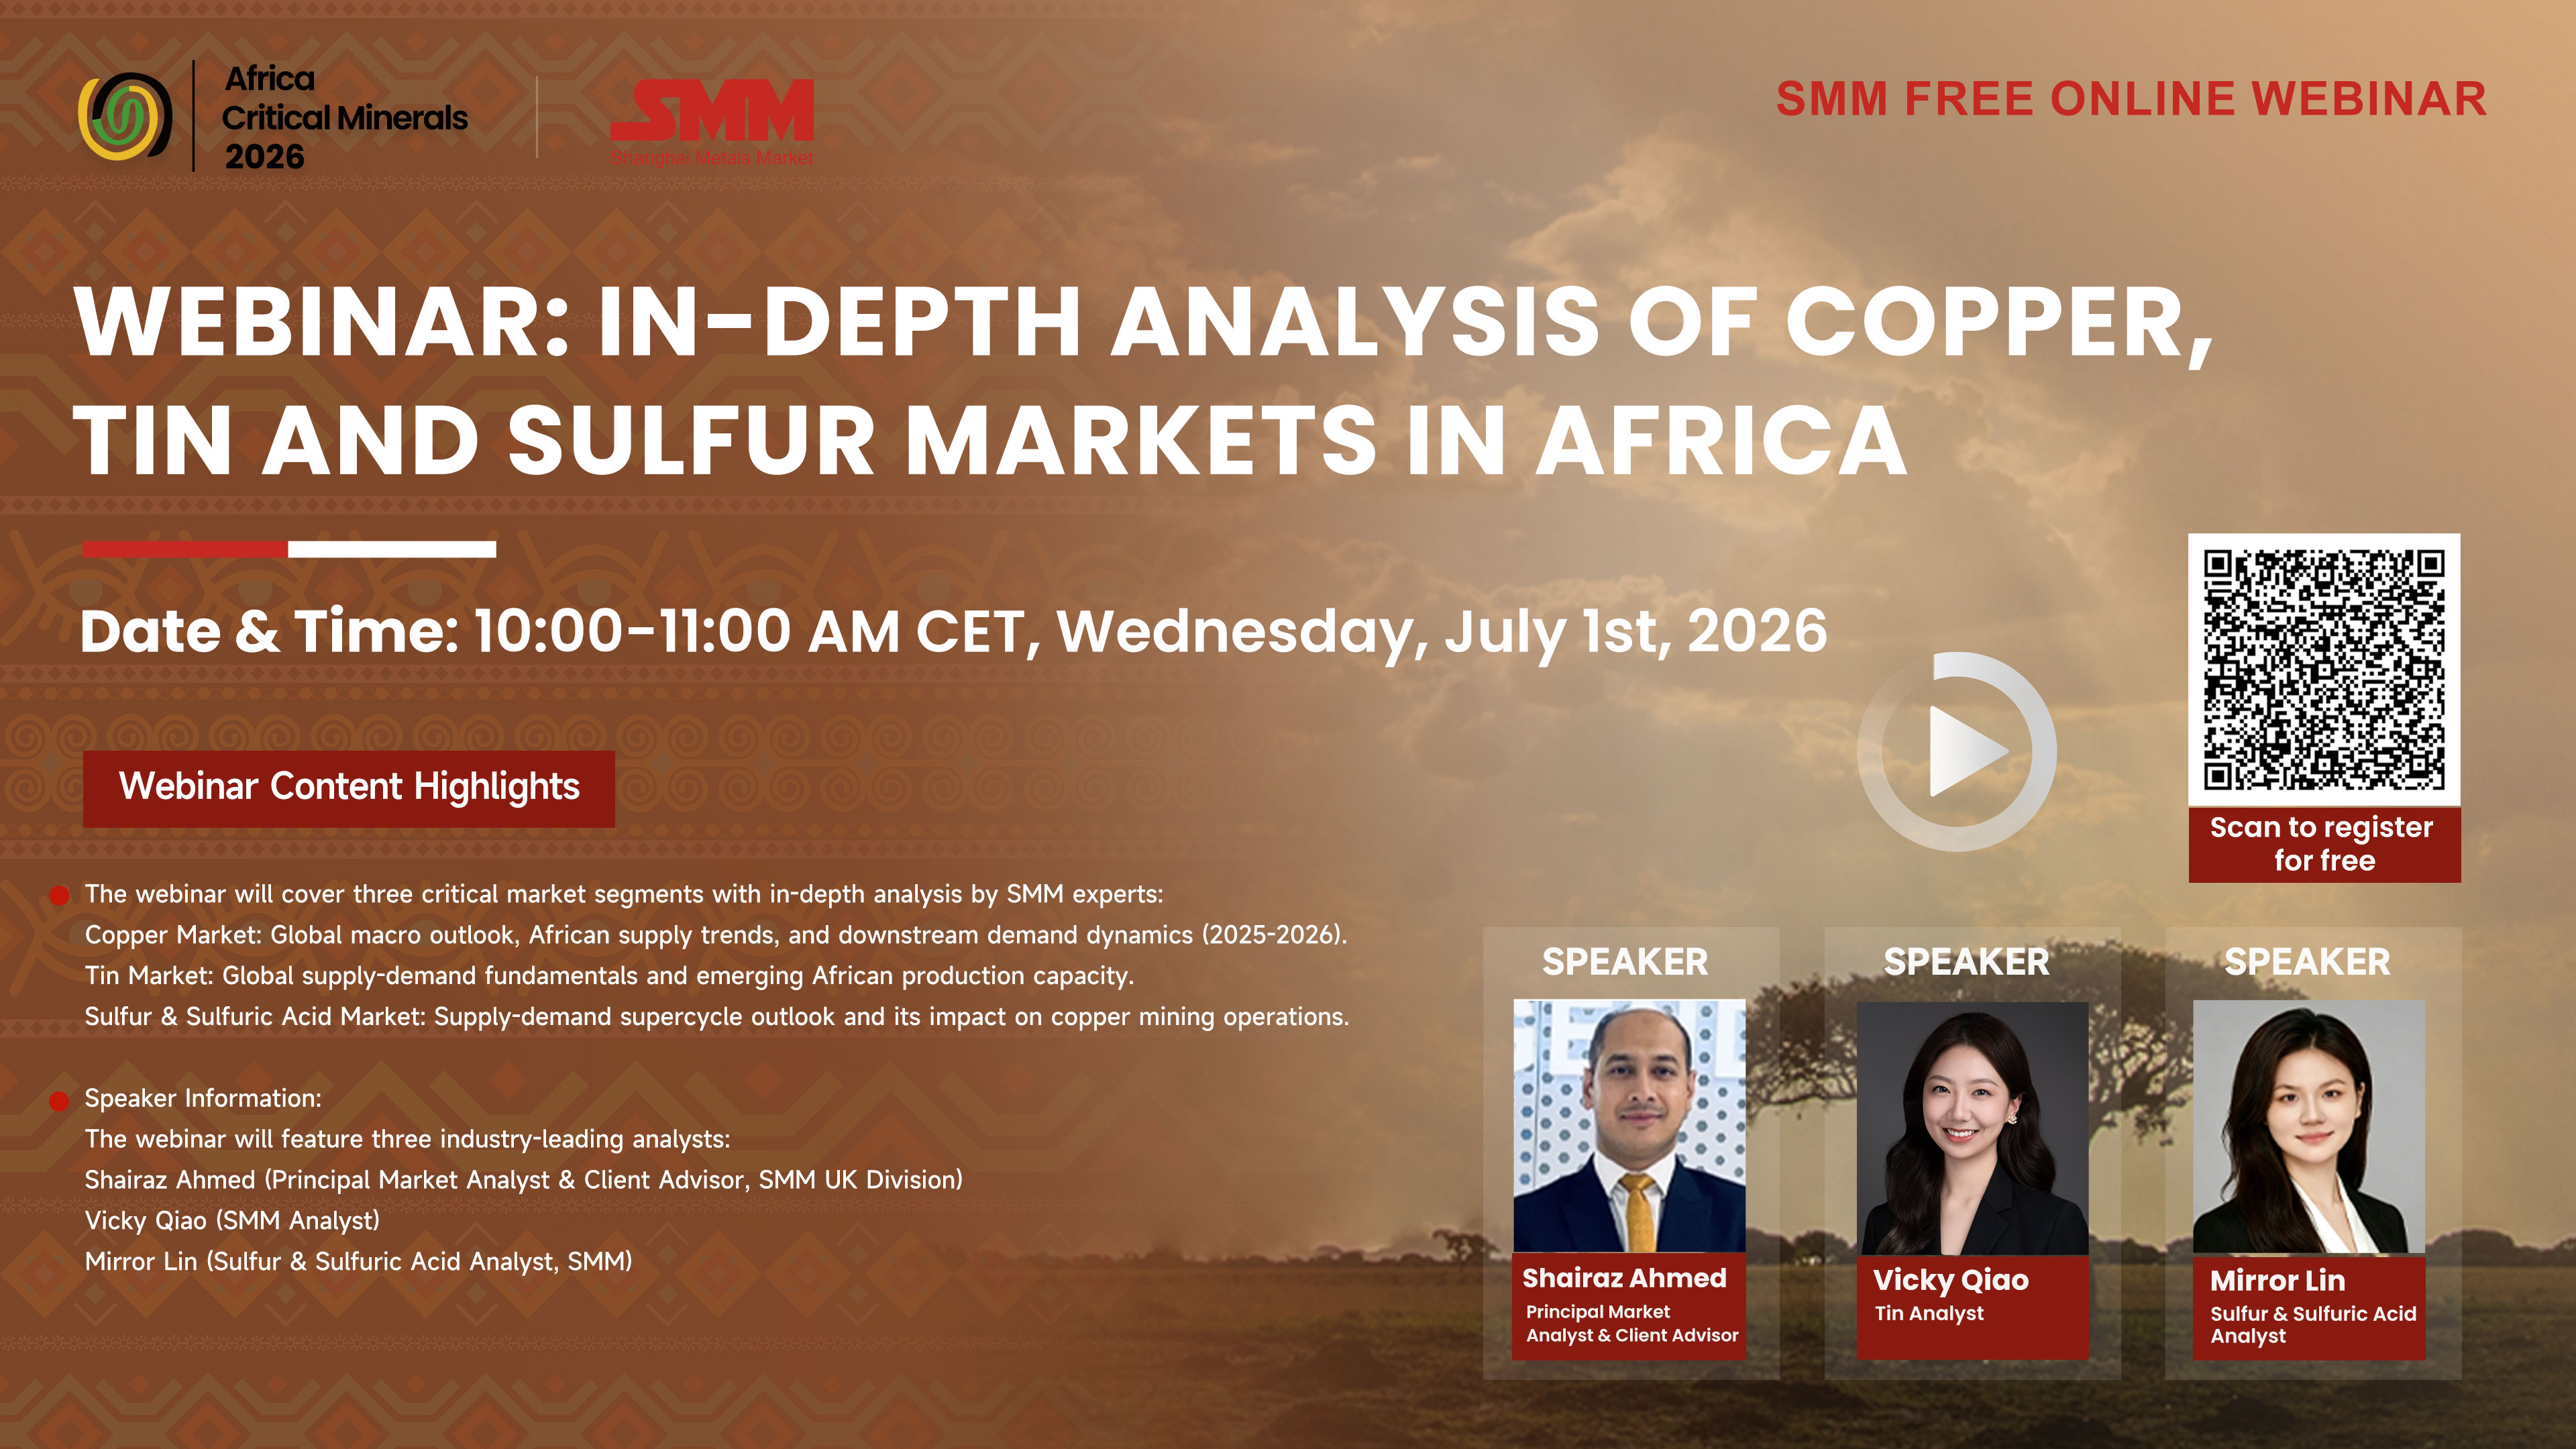 WebinarJul 1, 16:00 - 23:59 (GMT+8)
 WebinarMar 14, 16:00 - 23:59 (GMT+8)
 WebinarNov 6, 17:00 - 23:59 (GMT+8)